Key takeaways
- A bank reconciliation compares the cash balance in your general ledger with the bank statement and explains every difference, so both sides reach the same adjusted balance.
- In the worked example below, a company reconciles three bank accounts at October 31, 2026, and needs five journal entries, all for book-side items.
- Under UCC § 4-404, a bank doesn't have to pay a check presented more than six months after its date, so old outstanding checks need follow-up, not another month on the reconciliation.
A bank reconciliation is the process of comparing the cash balance in your general ledger with the balance on your bank statement and explaining every difference. Getting bank reconciliation right gives you a cash number you can defend, catches errors and fraud early, and keeps your team audit-ready. This guide covers the statement and its formula, the steps, a worked example, the entries, a template, and old items.
What is a bank reconciliation?
A bank reconciliation matches the cash account in your books, sometimes called the cash book, with the bank's record of the same account. It lists the reason for each difference. Doing it every month for every bank account gives you an accurate cash balance before you close the books.
- Balance per bankThe ending balance on the bank statement for the period
- Balance per booksThe ending balance of the cash account in your general ledger (GL)
- Adjusted balanceThe true cash balance both sides reach once every difference is accounted for
The two balances rarely match on day one, because the bank records some items before you do, such as fees and interest. You record others before the bank does, such as a check the vendor hasn't deposited yet.
Reconcile every bank account at least monthly, as one of the first tasks of the close. You can reconcile high-volume accounts weekly or even daily to catch problems sooner.
What is a bank reconciliation statement?
A bank reconciliation statement is the schedule that shows both balances, every reconciling item, and the adjusted balance they reach. It's also called a bank rec, and it's the document your reviewer signs and your auditors ask for.
The statement has four parts: the bank balance, its adjustments, the book balance, and its adjustments. The formula is the same for every account:
- Bank sideBalance per bank + deposits in transit − outstanding checks ± bank errors = adjusted bank balance
- Book sideBalance per books + interest and collections − fees and NSF checks ± book errors = adjusted book balance
When the adjusted bank balance equals the adjusted book balance, the account is reconciled. That adjusted balance is the cash figure that belongs on your balance sheet at period end.
| Bank side | Book side |
|---|---|
| Balance per bank statement | Balance per general ledger |
| Add: Deposits in transit | Add: Interest earned, collections by the bank |
| Less: Outstanding checks and payments | Less: Bank fees, NSF (returned) checks |
| Add or less: Bank errors | Add or less: Book errors |
| Adjusted bank balance | Adjusted book balance |
How do you do a bank reconciliation?
A bank reconciliation takes five steps: get both balances, match deposits, match payments, record the bank-only items, and review the result. Following the same steps for every account keeps the work consistent across preparers and entities.
- Get both balancesPull the bank statement and the GL cash balance for the same account and the same date. This is the first step, and a mismatch in dates creates false differences
- Match depositsTick each deposit in your books against the bank statement, and list deposits you recorded that the bank hasn't, as deposits in transit
- Match paymentsTick each check, ACH, and wire against the statement, and list payments the bank hasn't cleared, as outstanding checks and payments
- Record bank-only itemsList fees, interest, returned checks, and errors that appear on only one side, and prepare a journal entry for each item on the book side
- Review and sign offConfirm the adjusted balances agree, attach the support, and have a reviewer who didn't prepare the reconciliation approve it
Before you start, trace last month's reconciling items. Each prior-month deposit in transit and outstanding check should clear on this month's statement. Anything that didn't is the first thing to investigate.
Bank reconciliation example: One company's October
A worked example shows how one month's reconciliations fit together.
Example
A software company with about $80 million in annual revenue reconciles its three bank accounts at October 31, 2026. All amounts are illustrative.
| Account | Balance per bank | Balance per books | Adjusted balance | Entries needed |
|---|---|---|---|---|
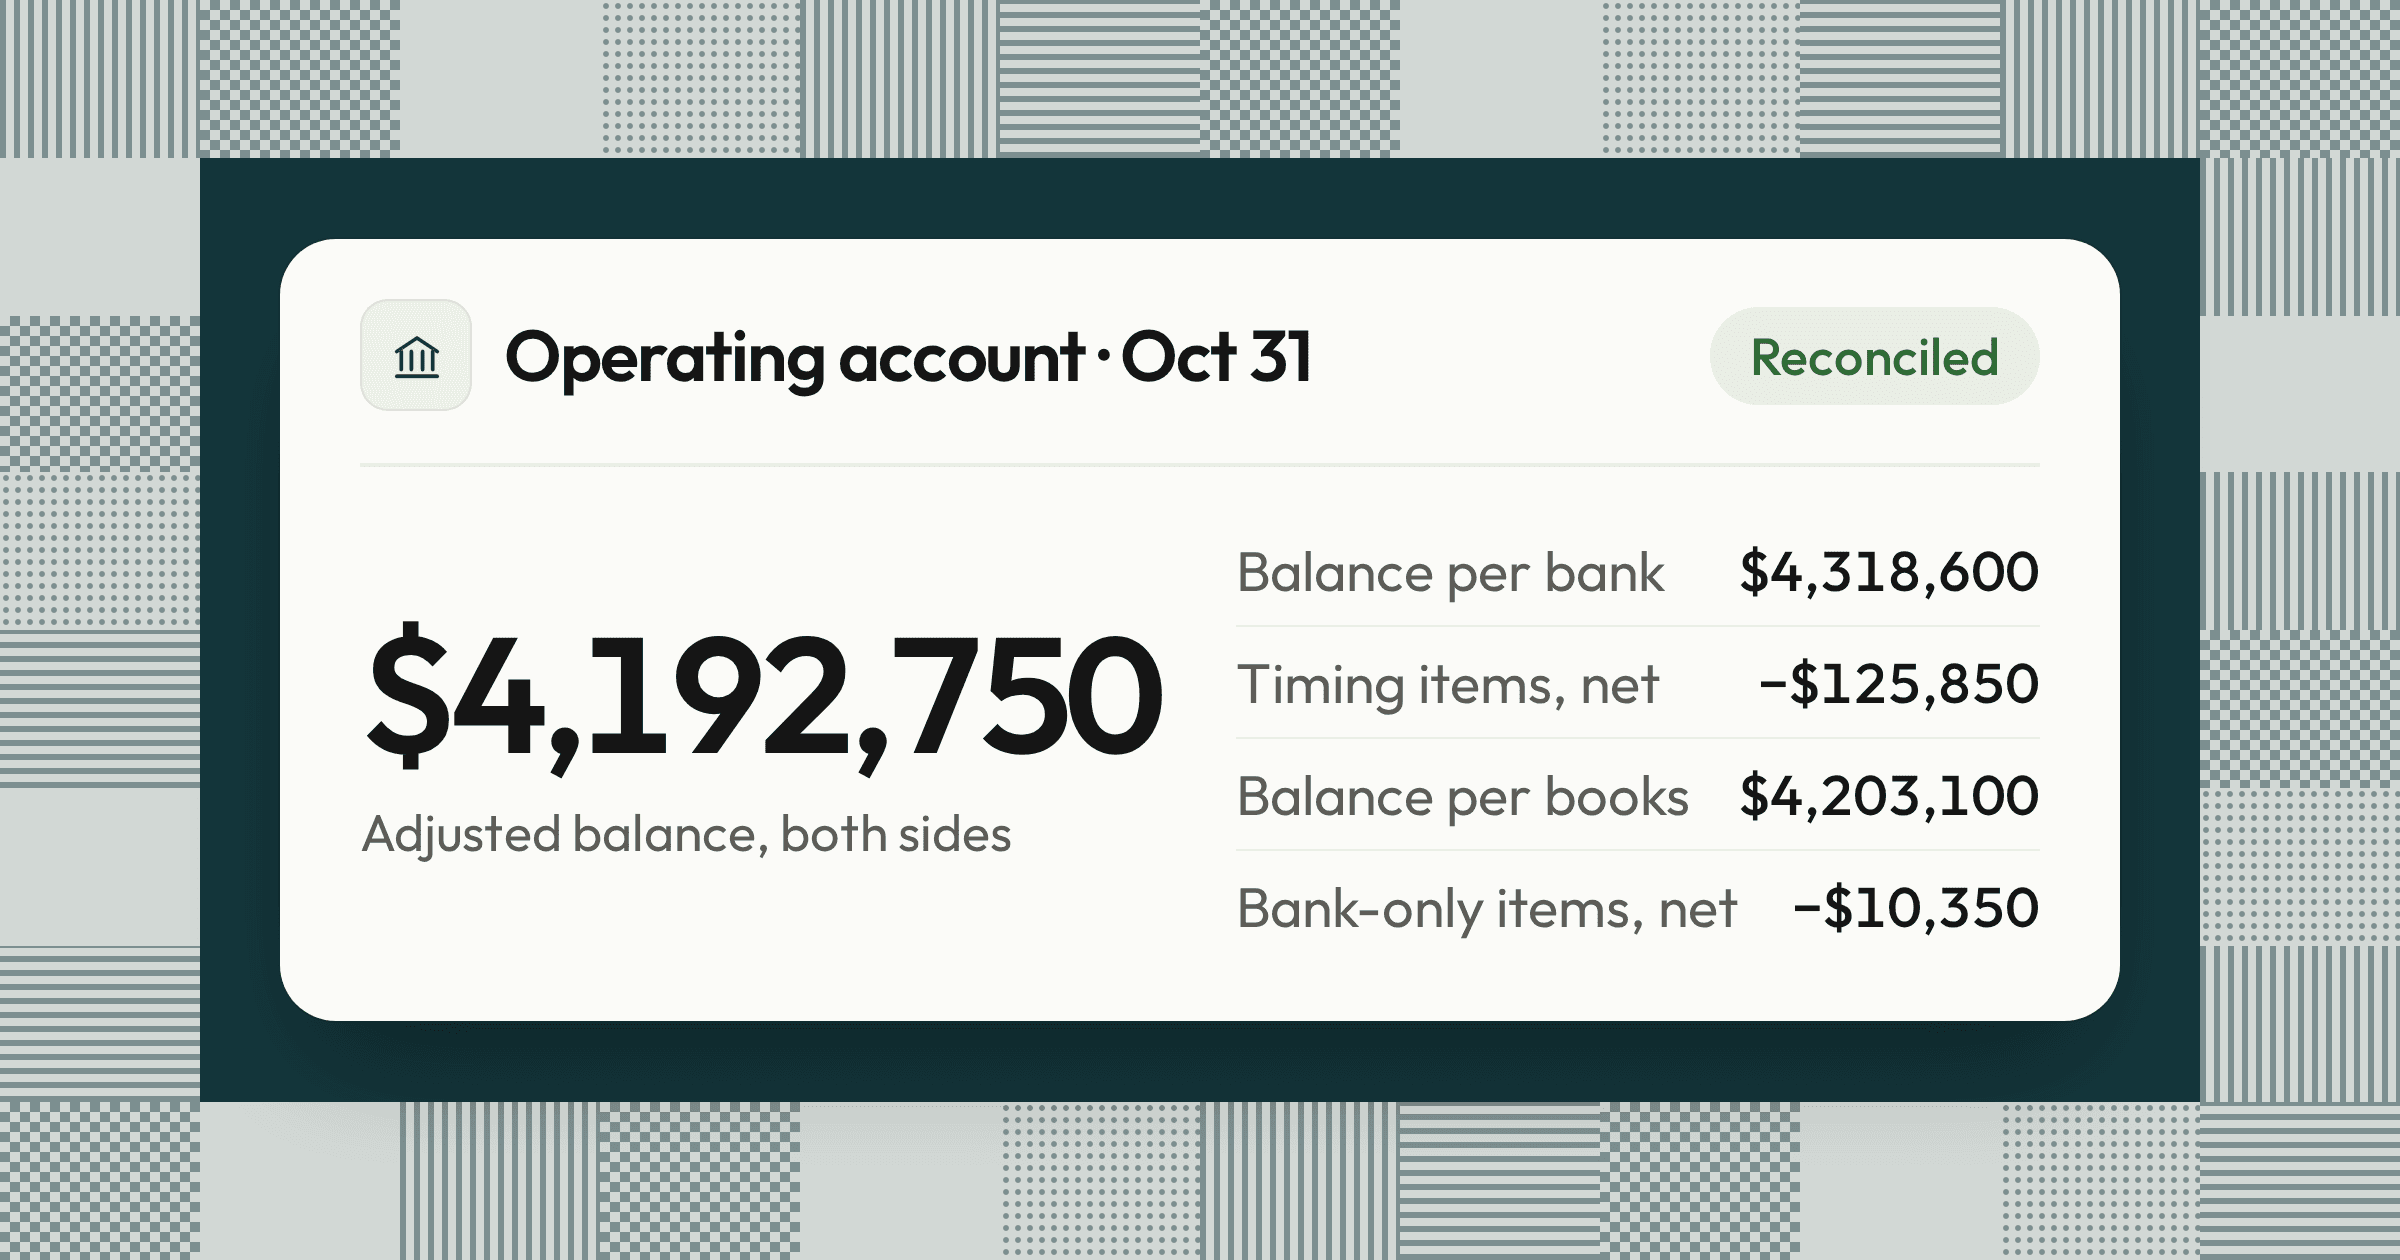
| Operating account | $4,318,600 | $4,203,100 | $4,192,750 | 4 |
| Payroll account | $616,200 | $612,000 | $612,000 | 0 |
| Money market account | $2,500,000 | $2,491,750 | $2,500,000 | 1 |
The payroll account differs only by $4,200 of payroll checks employees haven't cashed, so it needs no entry. The money market account is missing $8,250 of October interest the bank credited. The fix is a debit to cash and a credit to interest income for the same amount.
The operating account has the most activity, so its bank reconciliation statement shows every type of item:
| Operating account, October 31, 2026 | Amount |
|---|---|
| Balance per bank statement | $4,318,600 |
| Add: Deposit in transit, customer wire recorded October 31 | $142,500 |
| Less: Outstanding payments (check 10418 $18,350, October 31 ACH vendor run $248,000, check 9876 dated April 14 $2,000) | −$268,350 |
| Adjusted bank balance | $4,192,750 |
| Balance per general ledger | $4,203,100 |
| Add: Interest earned | $3,860 |
| Less: Bank service fees | −$1,450 |
| Less: Customer check returned for nonsufficient funds (NSF) | −$12,400 |
| Less: Check 10397 recorded as $6,480, cleared as $6,840 | −$360 |
| Adjusted book balance | $4,192,750 |
The bank side works out as $4,318,600 + $142,500 − $268,350 = $4,192,750. The book side works out as $4,203,100 + $3,860 − $1,450 − $12,400 − $360 = $4,192,750, so the account is reconciled.
Prepared by Close Agent
- Balance per bankStatement at 31 Oct4,318,600.00
- Balance per books10100 · Operating account4,203,100.00
- Book sideCustomer check returned, NSFReturned by the bank for nonsufficient funds; reinstate the customer's balanceStatement item 11812,400.00Needs review
- Book sideCheck 10397 recorded as 6,480.00, cleared as 6,840.00Transposed digits: the difference divides by 9Check 10397360.00Needs review
- Bank sideCheck 9876 dated 14 Apr still outstanding200 days old, past the six months a bank must honorCheck 98762,000.00Needs input
- Bank sideDeposit in transit, customer wire recorded 31 OctTiming: expected on the next statementWire 31 Oct142,500.00Verified
Adjusted balance, both sides4,192,750.00
The $360 error is a transposition, and its size gives it away: a difference that divides evenly by 9 can mean two swapped digits.
Which bank reconciliation items need a journal entry?
Only the items on the book side need a journal entry, because your books haven't recorded them correctly yet. Bank-side items, such as deposits in transit and outstanding checks, are timing differences that clear on their own.
| Item | Side | Effect on balance | Journal entry? |
|---|---|---|---|
| Deposit in transit | Bank | Increases bank balance | No |
| Outstanding check or payment | Bank | Decreases bank balance | No |
| Bank error | Bank | Either | No, ask the bank to correct it |
| Interest earned | Book | Increases book balance | Yes |
| Collection by the bank, such as a customer payment to a lockbox | Book | Increases book balance | Yes |
| Bank fee | Book | Decreases book balance | Yes |
| NSF or returned check | Book | Decreases book balance | Yes |
| Book error | Book | Either | Yes |
The operating account in the example needs four entries, and the money market account needs one:
| Account | Debit | Credit |
|---|---|---|
| Record operating account interest | ||
| Cash | $3,860 | |
| Interest income | $3,860 | |
| Record bank service fees | ||
| Bank fees expense | $1,450 | |
| Cash | $1,450 | |
| Reinstate the customer balance for the NSF check | ||
| Accounts receivable | $12,400 | |
| Cash | $12,400 | |
| Correct check 10397 | ||
| Accounts payable | $360 | |
| Cash | $360 | |
| Record money market interest | ||
| Cash | $8,250 | |
| Interest income | $8,250 | |
After these entries, the operating account's GL balance is $4,203,100 + $3,860 − $1,450 − $12,400 − $360 = $4,192,750, which matches the adjusted balance. For how these entries fit with the rest of the month's adjustments, see Month-end journal entries: Examples and what to review.
October bank reconciliation · Operating account book-side items
- Dr 61800 · Bank fees expense1,450.00
- Dr 12000 · Accounts receivable12,400.00
- Dr 20000 · Accounts payable360.00
- Cr 42000 · Interest income3,860.00
- Cr 10100 · Operating account10,350.00
- Each side14,210.00
Bank reconciliation workpaper, October 2026
What are the types of bank reconciliation?
There are three methods of preparing a bank reconciliation: adjusted balance, bank-to-book, and book-to-bank. Choosing one method for every account makes your reconciliations easier to review.
- Adjusted balance methodAdjusts both the bank and book balances to the true cash balance, as in the example above. It shows which items need entries, so it's the easiest format to review
- Bank-to-book methodStarts with the bank balance and adjusts it to agree with the GL balance
- Book-to-bank methodStarts with the GL balance and adjusts it to agree with the bank balance
Two related reconciliations come up in the same searches. A three-way reconciliation, used for trust and escrow accounts, ties the bank statement, the GL, and the total of the individual client ledgers.
A proof of cash goes further than a bank reconciliation. It reconciles the opening balance, receipts, payments, and closing balance for the whole period, so it catches errors that offset within the month. Auditors use it when they need more assurance over cash.
What should a bank reconciliation template include?
A bank reconciliation template, whether in Excel or in close software, should let someone outside your team see both balances, every reconciling item, and who signed off. Using one template for every bank account makes review faster and audit requests easier to answer.
- HeaderEntity, bank name, account number (last four digits), GL account, period end, and currency
- BalancesBalance per bank with the statement date, and balance per books with the trial balance run date
- Bank-side itemsEach deposit in transit and outstanding payment with its date, reference, amount, and age in days
- Book-side itemsEach fee, interest credit, returned check, and error, with the journal entry that records it
- ProofThe adjusted bank balance, the adjusted book balance, and an unexplained difference that should be $0
- Sign-offPreparer and reviewer names and dates, with the reviewer different from the preparer, for example a staff accountant who prepares it and a controller who reviews it
In an Excel bank reconciliation format, keep the bank statement export on one tab, the GL cash detail on a second, and the statement on a third. Formulas on the statement tab then add and subtract the listed items, and the unexplained difference cell shows $0 when the account is reconciled.
For where bank reconciliations sit in the close, see Month-end close process. For each reconciliation task with its owner and reviewer, see Month-end close checklist.
Cash and bank
- Bank reconciliation · Operating accountClose AgentIn reviewDWD 1
- Bank reconciliation · Payroll accountClose AgentSigned offAWD 1
- Bank reconciliation · Money market accountClose AgentSigned offAWD 1
- Returned check follow-upClose AgentIn progressAWD 2
- Stale-dated check reviewClose AgentIn progressDWD 2
What do you do with old outstanding checks and deposits in transit?
Investigate any reconciling item that hasn't cleared within 30 days, because a true timing item should clear on the next statement. Carrying the same items forward month after month hides errors and makes the cash balance harder to defend.
- Deposits in transitA deposit should reach the bank within a few business days. If one is still open at the next month-end, check whether it was lost, rejected, posted to another account, or recorded twice
- Outstanding checksContact the payee once a check reaches the age your policy sets, such as 90 days. Under UCC § 4-404, a bank isn't obliged to pay a check presented more than six months after its date, so a check like 9876 in the example needs a decision
- Voiding a checkIf the payee confirms it's no longer owed or you reissue it, void the original with a debit to cash and a credit to accounts payable or the original expense
- Unclaimed fundsIf you can't reach the payee, the money isn't income. State unclaimed property laws require you to report and remit it after a dormancy period that varies by state
Age each item from the date it first appeared, not from the current reconciliation. A short policy that names the age at which items escalate to the controller gives your reviewer and your auditors one rule to test.
Can bank reconciliation be automated?
Yes, bank reconciliation software can automate the work in stages, starting with transaction matching and moving to exceptions and entries. Automating the matching first frees your team for the items that need judgment.
- Bank feedsStatement data flows into your accounting system daily through a bank connection or file import, instead of a monthly download
- MatchingRules match deposits and payments to GL entries by amount, date, and reference, and leave only the exceptions
- ExceptionsEach unmatched item is listed with its amount, date, and likely cause, such as a fee, a returned check, or a transposition
- Entries and reviewEntries for book-side items are prepared for approval, and a named reviewer signs off the reconciliation
In NetSuite, you import bank data and apply matching rules on the Match Bank Data page. You then complete the reconciliation on the Reconcile Account Statement page. For a wider look at where AI helps across the close, see Does AI make the month-end close more accurate? What the evidence shows. For the trial balance review that follows reconciliations, see Post-closing trial balance: Examples, types, and when to prepare it.
How we approach it
Our Close Agent reconciles every bank account as a task on your close checklist. It matches every statement line to the ledger and shows each difference with its amount, date, source, and reference. For book-side items, it prepares the entry and the workpaper. When a statement is missing, it stops and asks for it, and nothing posts to your ERP until a named approver signs off. If you want your bank reconciliations prepared before your team starts the close, explore our Close Agent.
Share this article